by
Yohance Harrison
May 12, 2023

Most people assume the hard part of financial planning is helping clients save enough money. This episode argues the opposite. For a lot of successful savers, the harder part starts after the saving has worked.
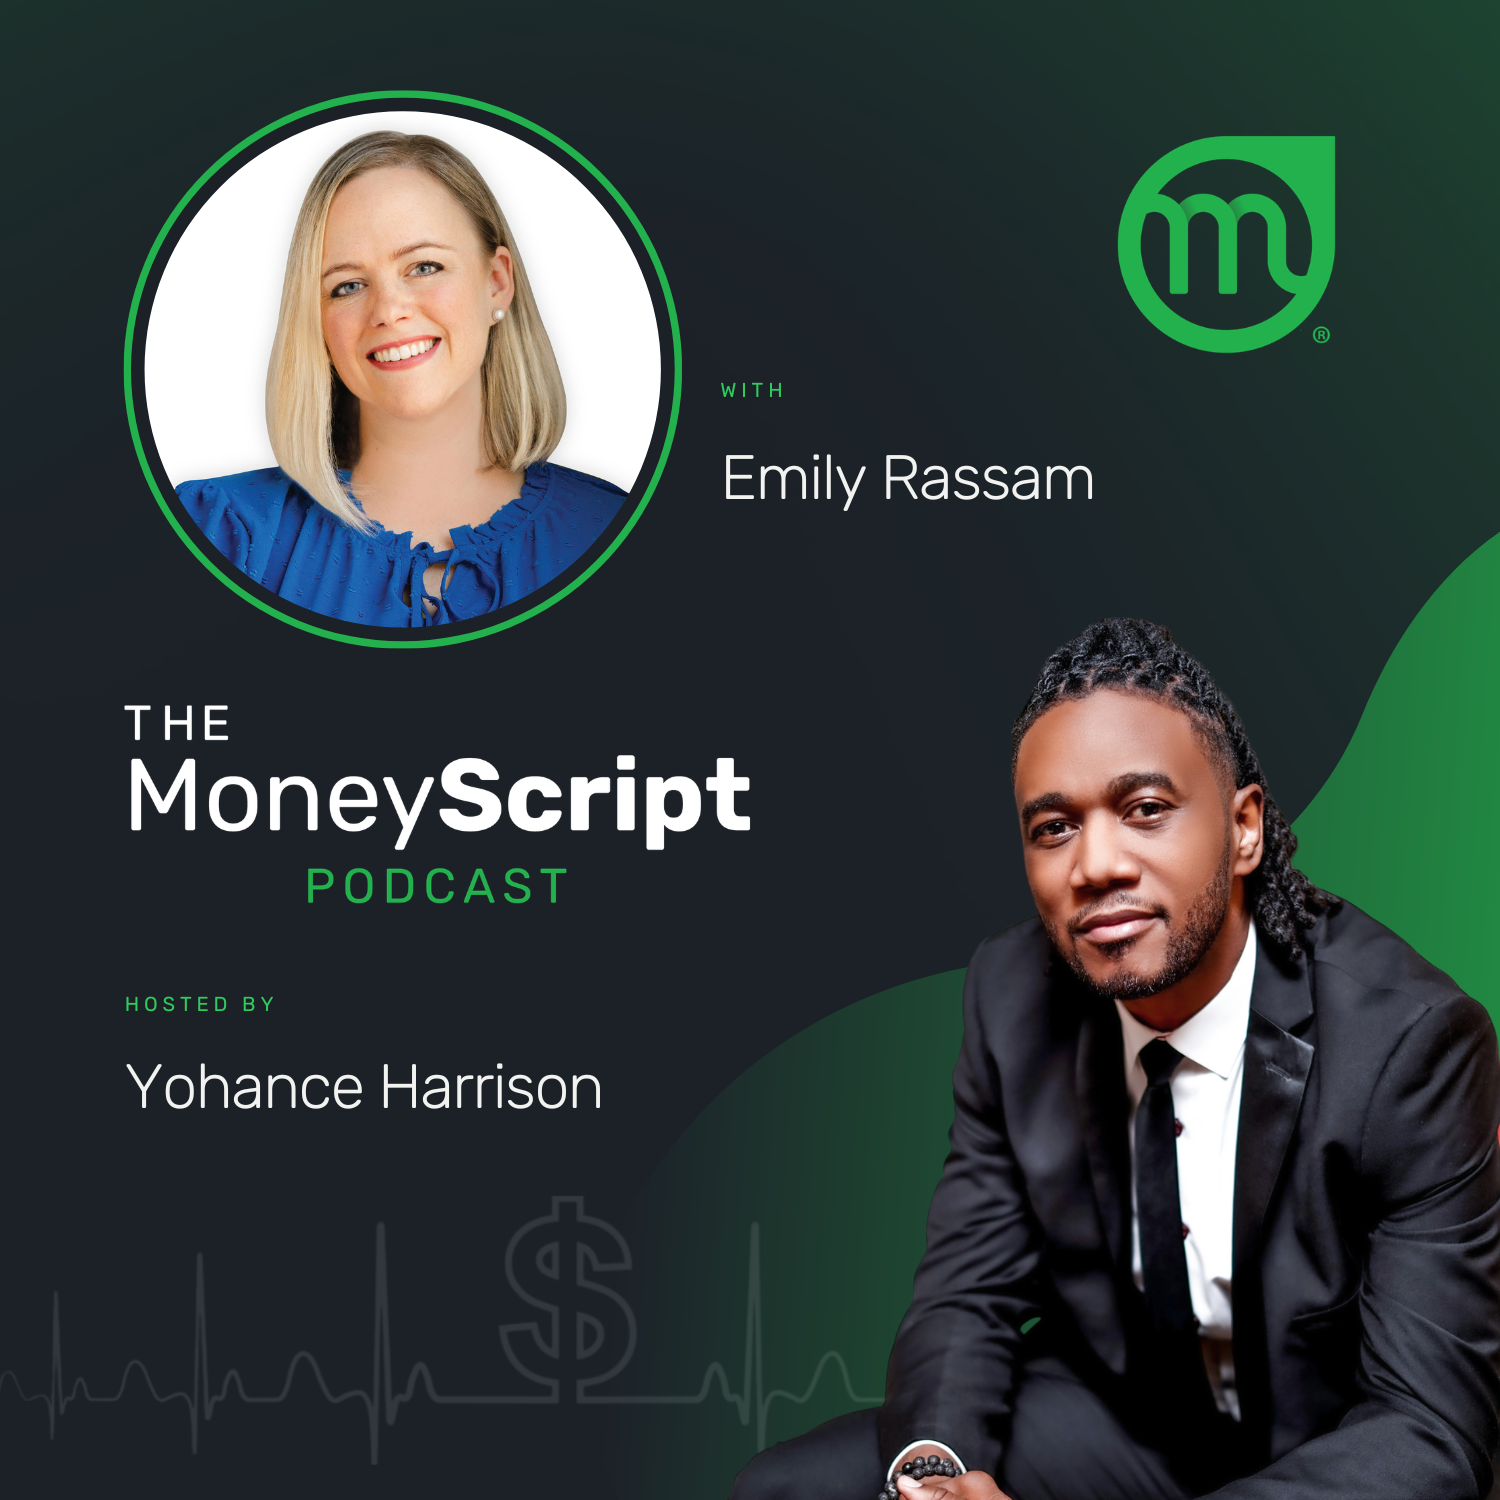
That tension sits at the center of this Money Script Podcast conversation between Yohance Harrison and Emily Rassam. The question sounds simple: why is it so hard to get clients to spend their money? But the answer reaches into behavior, identity, fear, family, work, retirement, and what people think money is for in the first place.
Emily explains that many clients spend decades building one financial muscle. Money goes into the 401(k), 403(b), IRA, brokerage account, or savings account. The habit is one-directional. Save more. Delay gratification. Be responsible. Then retirement arrives and the plan suddenly asks them to reverse the flow. Even when the math works, that reversal can feel wrong. Emily says it can be “physically painful” for clients to start taking money out.
That point matters because it shows the limits of spreadsheets alone. Yohance projection may show someone is on track to end life with tens of millions of dollars. The planner can point to Monte Carlo results, withdrawal rates, and account balances. None of that guarantees the client will feel safe enough to spend.
That’s where the conversation becomes especially useful for advisors and thoughtful savers. Emily doesn’t frame spending as a technical issue alone. She treats it as an emotional transition. Before she pushes clients to spend more, she tries to understand their “security blanket” number — how much they need in checking, savings, and other accounts to feel okay. That’s a subtle but important move. If a plan makes someone feel depleted, they won’t follow it, no matter how elegant the math looks.
The episode also offers a memorable way to talk about over-saving. Emily describes clients who want to keep working just to hit a specific number, even though nothing meaningful will change in their lives. When she asks whether they’ll upgrade the house, buy more cars, travel more, or change anything at all, sometimes the answer is no. Her blunt summary lands because it’s true: “You’re going to die with more money.”
That line works because it forces the real issue into the open. If more money won’t change how someone lives, why is the extra accumulation still the goal?
From there, the episode shifts into one of its strongest themes: money needs a purpose. Emily repeatedly brings clients back to what they actually want their money to do. That can mean spending on themselves, helping children, supporting charities, improving quality of life, or creating family experiences. Without that connection, wealth just sits there as a scorecard.
One of the best framing devices in the episode is Emily’s line: “All money is going to be spent.” It will be spent by the client now, by the client later, by beneficiaries, or by the government. That idea neatly reframes financial planning. The question isn’t whether the money gets used. The question is who gets to use it, when, and for what.
That leads to one of the show’s most practical tools: better questions. Emily shares a prompt she uses with clients: if $50 million landed in your bank account tomorrow, taxes already paid, what would you do? The point isn’t literal planning at that dollar amount. The point is to get around the internal limits people impose on themselves. Dreaming at that scale sometimes reveals desires clients have never admitted out loud. In one example, a client who insisted nothing would change eventually admitted that a beach home for children and grandchildren sounded wonderful. That gave the planner something real to work with.
The lesson is bigger than the hypothetical. Good planning often depends on asking questions that bypass the obvious, socially acceptable answer. “I don’t need anything” may sound disciplined, but it can also hide uncertainty, guilt, or lack of imagination.
The episode gets even more useful when it turns to clients who may not have enough. This part keeps the discussion grounded. Not everyone is headed toward a giant surplus. Some retirees need a different kind of conversation: not how to spend more, but how to make the plan work.
Emily’s approach here is notably careful. First, check the math. Confirm expenses weren’t double counted and assumptions are clean. Then show the client the path to a workable plan. She avoids playing “budget police.” She doesn’t want to be the person who tells someone to stop traveling or cut the one activity that keeps them healthy and sane. Instead, she focuses on priorities and tradeoffs. What matters most? What can move? Can inflows rise? Can outflows come down? Can the client decide where the cuts belong rather than having the planner dictate them?
That collaborative posture feels like one of the most durable ideas in the episode. Financial planning works better when clients keep agency. People are far more likely to act on tradeoffs they chose than restrictions they resent.
Another valuable section covers how Emily coached clients through market stress, including the 2008 crisis and the COVID selloff. Her explanation is plain and practical. Different money has different jobs. Some assets are short-term spending assets. Some are long-term growth assets meant for ages 85 or 92, not today. Segregating those roles can keep clients from panicking when they see a total balance fall. This is classic good advice, but it lands because she describes how it sounds in real conversations rather than abstract portfolio theory.
The quality-of-life thread runs through the whole episode. Emily makes the point that better spending doesn’t always mean bigger spending. Sometimes it looks like hiring help, getting healthcare support, easing caregiving strain, or addressing a lingering physical issue. She gives a great example of a retired client caring for a spouse with cancer who resisted hiring a house cleaner because of old beliefs about what “hardworking” people should do. That’s the kind of money script that rarely shows up on a balance sheet but shapes behavior all the same.
That example captures what this episode does best. It moves beyond the numbers without abandoning them. The math matters. But the real work often happens where identity, memory, guilt, status, responsibility, and self-worth meet the financial plan.
The episode also gives listeners a window into Emily’s planning process. She names distinct meetings such as goals and values meetings, data confirmation, plan delivery, and Flourish meetings. The naming isn’t branding for branding’s sake. It reflects a structured effort to ask the right questions at the right time. Her Flourish meeting in particular stands out because it is intentionally “not about math.” It gives clients room to process abundance, imagine possibilities, and think beyond default accumulation.
That’s a smart reminder for advisors building a client experience and for consumers evaluating one. Yohance strong planning relationship usually needs more than one kind of meeting. There’s a difference between gathering data, delivering analysis, and helping someone imagine a better use of their life and money.
Late in the conversation, the topic shifts to writing and podcasting, but it still connects to the larger theme. Both speakers prefer authenticity over rigid scripting. Emily says her best writing comes when she feels genuinely interested and energized, not when she forces it into a pre-set block. Yohance says he likes podcast conversations to feel like real discovery rather than a checklist. That matters because the episode itself follows that principle. It feels exploratory, curious, and human.
For listeners searching for practical retirement planning insight, this is what makes the episode worth hearing. It doesn’t promise a hack. It surfaces the real questions people face when enough money exists but clarity does not. What is this money for? What would make life better now? How much security is enough? What do you want to witness while you’re still here instead of leaving everything for later?
If there’s a single takeaway, it’s this: the goal of financial planning is not simply to die with a large number. The goal is to use money intentionally in service of a life that actually feels lived. For some people, that means retiring sooner. For others, it means gifting earlier, supporting family, giving to charity, protecting time, or finally spending on care, health, and ease. For others still, it means facing the hard truth that the current plan needs tradeoffs.